Why the Purchase Price Is Only the Beginning
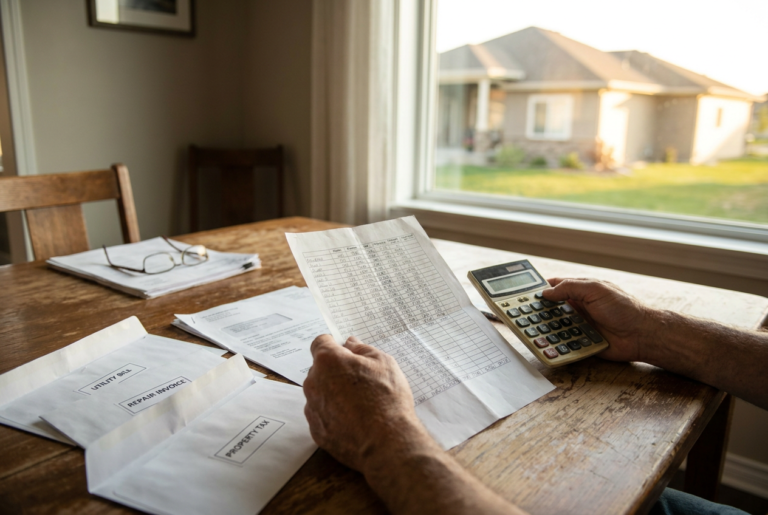
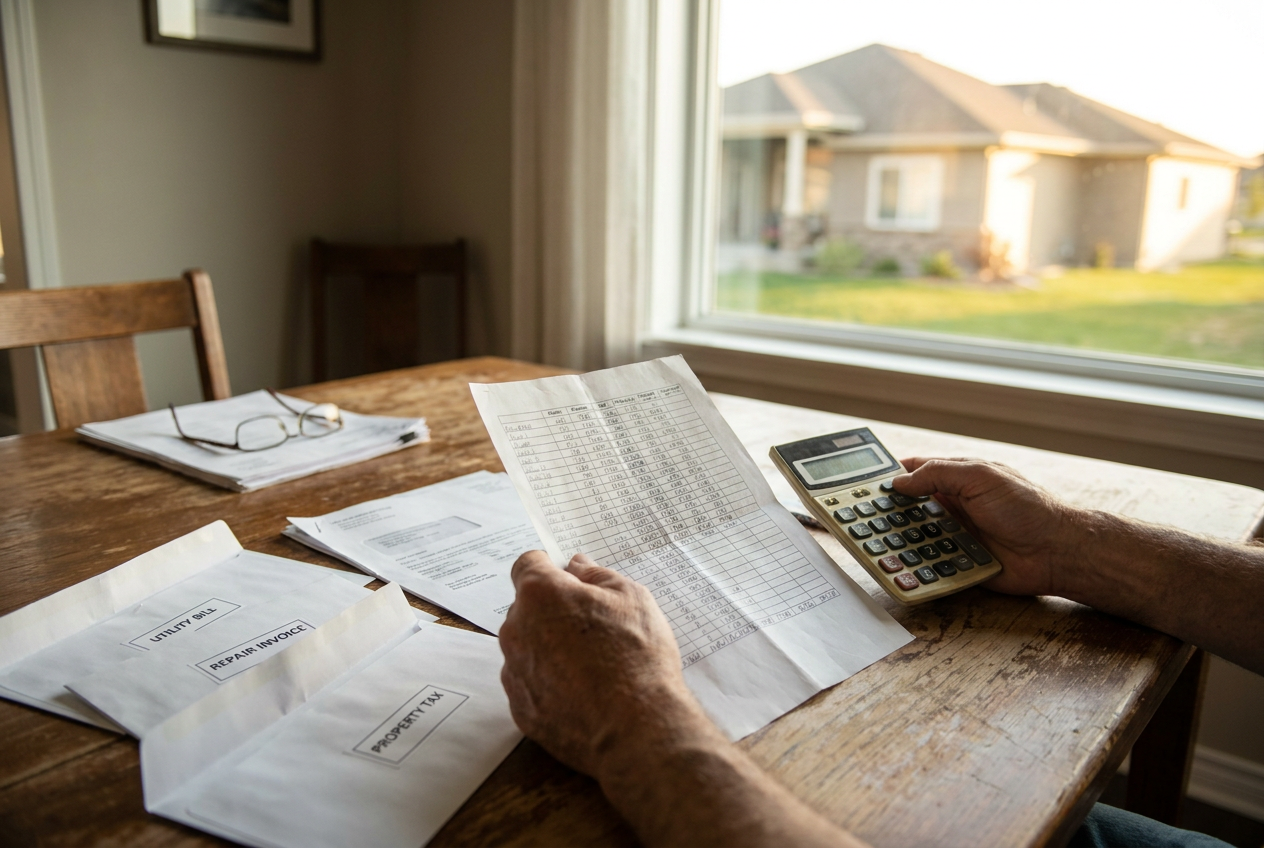
When you buy a house, the sticker price tells you very little about your actual monthly obligations. First-time buyers routinely focus on the mortgage principal and interest while ignoring ancillary expenses that easily add hundreds of dollars to your baseline budget. Property taxes, homeowners insurance, and municipal fees escalate annually. If you put down less than twenty percent, add private mortgage insurance to that total. Protect your finances by building a separate reserve fund immediately. Treat routine maintenance, unexpected roof repairs, and rising utility bills as fixed realities rather than occasional surprises.
The Recurring Costs That Add Up Every Year
Property taxes, homeowners insurance, and maintenance claims consume thousands annually beyond your principal and mortgage interest. Local tax assessments rise regularly, and insurance premiums surge by double digits in disaster-prone regions.
Set aside one percent of your home’s purchase value every year for upkeep. If you own a $400,000 house, that means budgeting $4,000 annually specifically for unexpected plumbing failures, roof leaks, or failing HVAC units. Ignoring this reserve forces reliance on high-interest credit cards when inevitable repairs strike.
One-Time and Surprise Costs to Budget For
Beyond yearly bills, sudden capital expenses can drain your savings within weeks of moving in. Budget immediately for municipal transfer taxes, utility hookup fees, and immediate code compliance updates.
When an aging sewer line backs up or a 15-year-old roof leaks during your first heavy rainstorm, you carry the entire repair bill. Contractors often charge emergency call-out rates averaging $250 per hour for urgent weekend fixes.
Keep a separate emergency fund equal to three percent of your purchase price. This buffer absorbs unexpected failures without forcing you into high-interest consumer debt.
Hidden Costs by Property Type and Location
Your geographic location and home style directly dictate your hidden overhead. Historic properties demand specialized tradespeople and custom materials, often doubling local repair estimates. If you purchase in a flood zone, mandatory hazard policies add up to three thousand dollars annually outside standard insurance. Meanwhile, suburban single-family houses feature private sewer lines or septic tanks that require professional pumping every three years, costing roughly four hundred dollars per visit. Condominiums and townhomes exchange exterior maintenance for mandatory monthly association fees that typically rise five percent each year to fund aging community roofs and shared parking lots.
A Simple Table: Typical Annual Hidden Costs
Review these average yearly outlays to gauge your actual financial exposure before signing a purchase contract:
| Expense Category | Typical Annual Cost | What It Covers |
|---|---|---|
| Property Taxes | $2,500 – $6,000 | Local municipal and school assessments |
| Homeowners Insurance | $1,200 – $3,000 | Structure replacement and liability coverage |
| Routine Maintenance | 1% to 2% of home value | HVAC servicing, gutter cleaning, minor repairs |
| HOA Dues | $2,400 – $6,000 | Community amenities, shared grounds upkeep |
How to Estimate Your True Housing Costs Before You Buy
Build a dedicated home reserve fund using the one-percent rule: set aside one percent of your purchase price annually for emergency repairs. Open a separate high-yield savings account exclusively for this fund before you make an offer. If you buy a $400,000 property, deposit at least $333 each month. Factor in local utility connection fees, pest inspection contracts, and lawn equipment purchases that add up during your first ninety days of occupancy. Run these exact figures through a personal spreadsheet to see how your monthly cash flow actually handles unexpected maintenance bills.
Frequently Asked Questions About Homeownership Hidden Costs
First-time buyers often ask what salary is required for a $400,000 house. Generally, lenders recommend an annual income of at least $90,000 to $100,000 to comfortably manage taxes, insurance, and maintenance alongside a mortgage. For a $1,000,000 property, you typically need an income exceeding $220,000.
Buyers frequently wonder what devalues a house the most. Deferred roof maintenance, chronic water intrusion, and structural foundation neglect cause the steepest drops in property value. Always allocate funds for immediate structural inspections before closing.
Turning Hidden Costs Into a Confident Decision
Owning a home should bring long-term stability, not constant financial panic. By anticipating property taxes, emergency repairs, and municipal fees before you make an offer, you protect your household from stress. Set aside dedicated cash reserves on day one. Treat your monthly housing budget as a baseline that includes maintenance, not just principal and interest. When you map out these expenses realistically, you retain full control over your finances and step into homeownership with absolute peace of mind.
Frequently Asked Questions
What salary is generally recommended to comfortably buy a $400,000 home?
Mortgage professionals typically advise earning an annual salary between $90,000 and $100,000. This threshold ensures you can comfortably cover ancillary housing expenses alongside your standard principal and interest payments.
How much money should buyers set aside annually for routine property upkeep?
Financial planners often recommend utilizing the one-percent rule, which involves saving one percent of the home’s total purchase price every year. Placing these funds into a dedicated high-yield account prevents unexpected repair bills from disrupting your household budget.
Why do historic properties typically carry higher maintenance expenses?
Older homes often require specialized craftsmanship and custom-ordered materials that standard contractors cannot easily supply. Consequently, routine preservation and emergency fixes on older architecture can easily double typical local repair estimates.
Do homeowners insurance premiums remain stable over the life of a loan?
Insurance rates frequently fluctuate and can surge by double-digit percentages, particularly in regions prone to natural disasters or severe weather events. Buyers must factor potential premium spikes into their long-term budgeting strategies.
What upfront financial obligations typically arise immediately after closing?
New buyers frequently encounter sudden capital outlays such as utility connection fees, municipal transfer taxes, and mandatory code compliance upgrades. Having liquid cash reserves ready prevents these initial surprises from draining your emergency savings.