Why the Real Cost of Pet Ownership Surprises Most Families
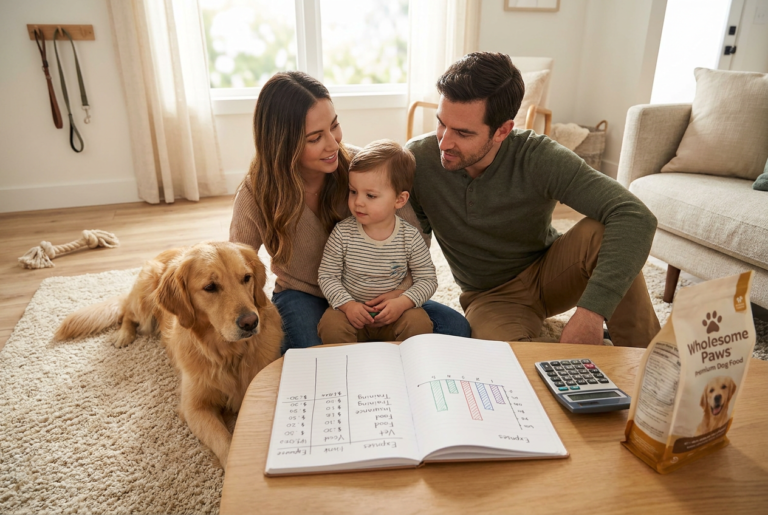
Most families budget for food and a single annual vet visit, assuming a dog or cat costs around fifty dollars a month. That estimate misses reality by hundreds of dollars. Over a pet’s lifetime, total expenses routinely range from fifteen to fifty thousand dollars.
Initial adoption fees and supplies are only the baseline. Ongoing expenses scale sharply due to routine medical care, dental cleanings, and specialized nutrition. When you factor in unexpected emergencies, boarding, and grooming, pet ownership requires a dedicated line item in your household budget. Understanding these actual figures beforehand ensures your family can provide consistent care without straining your finances.
Upfront Costs: What You Pay Before Your Pet Comes Home
Before your new pet crosses your threshold, initial expenses hit your checking account all at once. Adoption fees from local shelters typically range from fifty to three hundred dollars, covering initial vaccinations, microchipping, and spay or neuter surgeries. Private breeders cost significantly more, often exceeding one to two thousand dollars for purebred dogs.
Beyond the adoption or purchase price, you need essential gear. A sturdy crate, collar, leash, food bowls, and grooming tools average two hundred to four hundred dollars. Factor in immediate veterinary exams and initial parasite treatments, and your total startup investment lands between four hundred and fifteen hundred dollars before purchasing a single bag of daily food.
Ongoing Annual Costs: Food, Vet Care, Grooming, and Insurance
Once your pet settles in, monthly maintenance demands predictable cash flow. Expect to spend $150 to $350 monthly, depending on your animal’s size and medical needs. Premium food and routine preventive medications form the baseline. On top of that, budget $400 annually for wellness checks and vaccinations. If you own a breed requiring professional grooming every six weeks, add another $600 to $900 per year. Accident and illness insurance policies typically run $35 to $70 monthly, serving as a buffer against staggering veterinary bills. Tracking these recurring outlays ensures your household absorbs them without straining your core savings.
The Hidden and Emergency Expenses Most Budgets Miss
Routine food and vaccinations rarely break a household budget. Instead, unexpected incidents derail financial plans. Dental cleanings average $500 to $1,000 under general anesthesia, and boarding or pet-sitting fees quickly accumulate during family vacations at $30 to $60 daily. Emergency veterinary care represents the largest financial risk for owners. Treatable conditions like foreign-object ingestions or sudden illnesses routinely generate veterinary bills exceeding $2,000. Building an emergency reserve fund specifically for your animal prevents high-interest credit card debt when urgent medical needs arise unexpectedly.
The 3-3-3 Rule: What It Means for Your First Weeks (and Wallet)
Adopting a rescue animal involves an adjustment period known as the 3-3-3 rule: three days to decompress, three weeks to learn routines, and three months to feel at home. During these phases, expect extra spending. A stressed pet might destroy a $120 crate, ruin baseboards, or refuse standard food, requiring costly alternatives. Budget an extra $200 for specialized chews, pheromone diffusers, and temporary training aids during month one. Recognizing this transition timeline protects your household cash flow while helping your new companion settle safely into family life.
Costs Beyond Money: Time, Attention, and Lifestyle Trade-Offs
Financial spreadsheets only capture part of the equation. Owning a dog or cat demands daily hours of hands-on attention that alters your family calendar. You must factor in early morning walks, medication schedules, and daily feeding routines regardless of your work hours or fatigue levels. Travel requires booking a pet sitter or paying $40 to $60 nightly for boarding facilities, which adds hundreds of dollars to every family vacation. Spontaneous weekend getaways become complicated logistical hurdles. Evaluate these lifestyle shifts honestly before bringing an animal home, ensuring your household has the available hours to match the financial commitment.
Building a Realistic Pet Budget That Fits Your Family
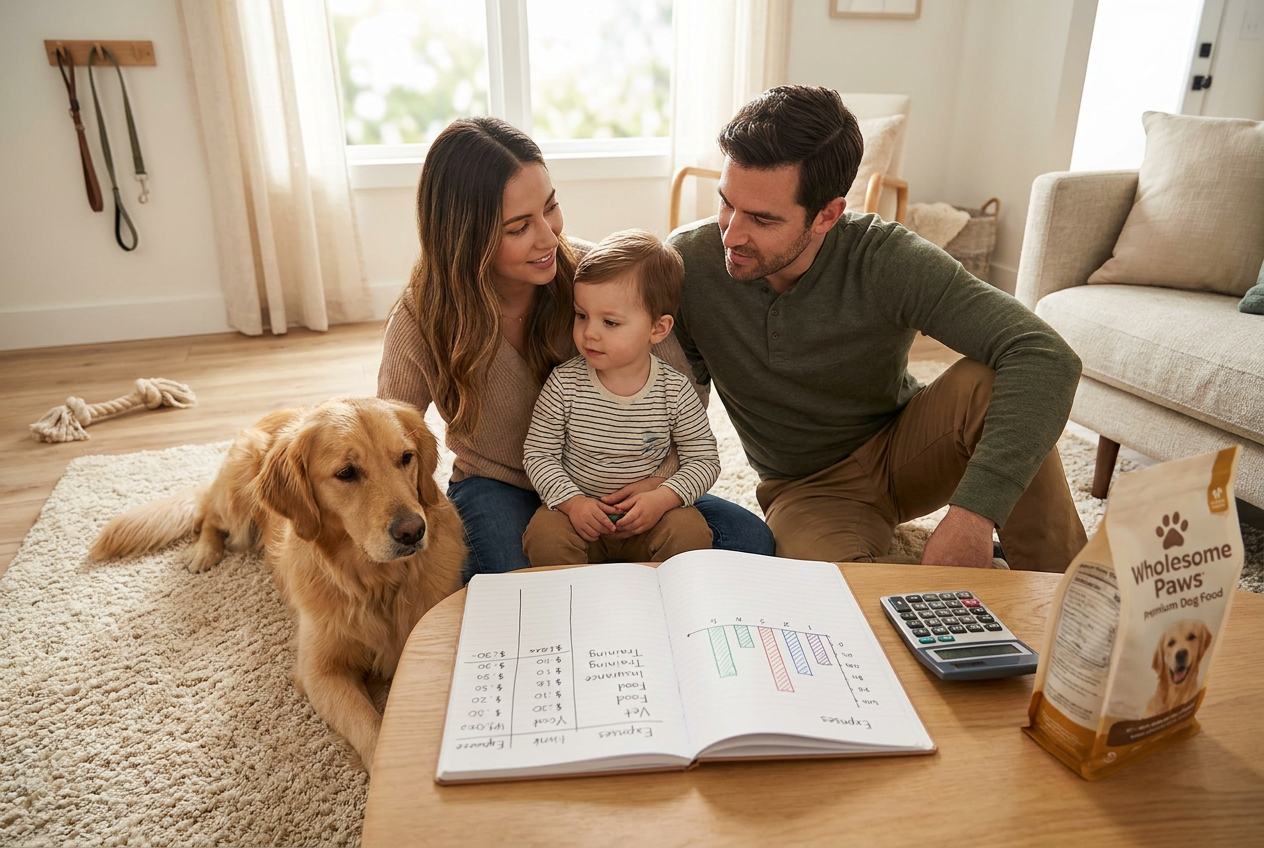
To protect your household finances, create a dedicated pet sub-account before bringing an animal home. Automatically transfer fifty to one hundred dollars each payday specifically for veterinary care and supplies, keeping these funds separate from your emergency savings. Track every dollar spent during the first ninety days to establish an accurate baseline for your pet ownership costs, adjusting your grocery or entertainment spending to absorb the new baseline. If this monthly allocation strains your current cash flow, delay adoption until your income and expenses stabilize, ensuring your family can provide care without financial distress.
When Pet Ownership Makes Financial Sense—and When to Wait
Welcoming a dog or cat makes financial sense when your cash flow comfortably absorbs a $3,000 emergency vet bill without touching your retirement savings or credit cards. If your household budget already stretches thin covering housing and groceries, pause and wait. Animals thrive on stability, and your financial peace matters just as much. Build an emergency fund first, test a pet-sitting routine for friends, and revisit adoption when your accounts show surplus. A deliberate timeline protects both your family’s financial future and your future companion’s well-being.
Frequently Asked Questions
How much do families typically underestimate pet ownership costs?
Most households budget strictly for basic food and a single annual checkup, assuming expenses remain under fifty dollars monthly. In reality, lifetime expenditures regularly stretch into the tens of thousands of dollars when accounting for long-term maintenance and care.
What initial expenses occur before bringing a rescue pet home?
Initial startup costs bundle several vital medical and administrative fees together at adoption. These mandatory charges generally cover spay or neuter procedures, electronic microchipping, and mandatory preliminary immunizations provided by shelters.
Why do unexpected medical procedures cost so much for pets?
Specialized veterinary treatments require advanced diagnostic equipment, sterile operating environments, and trained surgical personnel. Procedures like professional dental cleanings also mandate general anesthesia, which significantly increases the final clinic bill.
How does the 3-3-3 rule impact initial household spending?
The multi-week decompression period for rescue animals often triggers unplanned purchases for anxious pets. Families frequently need to buy replacement household items, specialized training tools, or calming aids while the animal adapts to its new environment.
What is the best strategy for managing unpredictable veterinary bills?
Establishing a separate savings sub-account protects your primary household funds from sudden medical emergencies. Automatically transferring a set amount each payday ensures you have a dedicated safety net ready for unexpected health crises.
When should a household postpone getting a pet for financial reasons?
Families should wait if their current monthly budget barely covers basic housing and living expenses without building savings. A safe adoption window requires enough disposable income to absorb a major veterinary emergency without relying on credit cards.