Why a Well-Being Budget Matters More Than a Financial One
Traditional budgets track bills, debt, and retirement savings, yet often ignore the physical and mental health expenses that keep you earning. A well-being budget shifts this paradigm. Borrowed from national economic models like New Zealand’s public funding approach—which prioritizes social indicators alongside fiscal data—this personal framework measures success by health and stability.
If chronic stress forces you to take unpaid leave, your traditional budget fails. By designating explicit funds for preventive care, mental health days, and family needs, you protect your primary asset: your capacity to work and live well.
Step 1: Audit Your Current Health and Happiness Spending
Pull your bank and credit card statements for the last ninety days. Categorize every dollar spent outside of fixed bills and housing into three columns: physical health, mental wellness, and social connection.
You will likely find hidden subscriptions, unused gym memberships, or frequent takeout orders driven by stress rather than hunger. For example, add up that daily four-dollar coffee run paired with a rushed bakery item—it often totals over one hundred dollars monthly. Recognizing where your money currently goes creates the baseline needed to build a realistic, intentional well-being budget tailored to your actual habits.
Step 2: Define Your Well-Being Priorities and Goals
Now that your past spending is mapped, separate genuine health needs from marketing noise. You do not need a boutique gym membership or premium supplements to feel well. Write down three specific areas that genuinely improve your daily life, such as physical mobility, stress management, or time with family pets. If outdoor walks clear your mind better than an expensive yoga class, prioritize footwear over studio fees. Rank these goals by their actual impact on your energy levels. This hierarchy stops you from funding habits that drain your bank account without improving your baseline health.
Step 3: Allocate Funds Across Physical, Mental, and Social Health
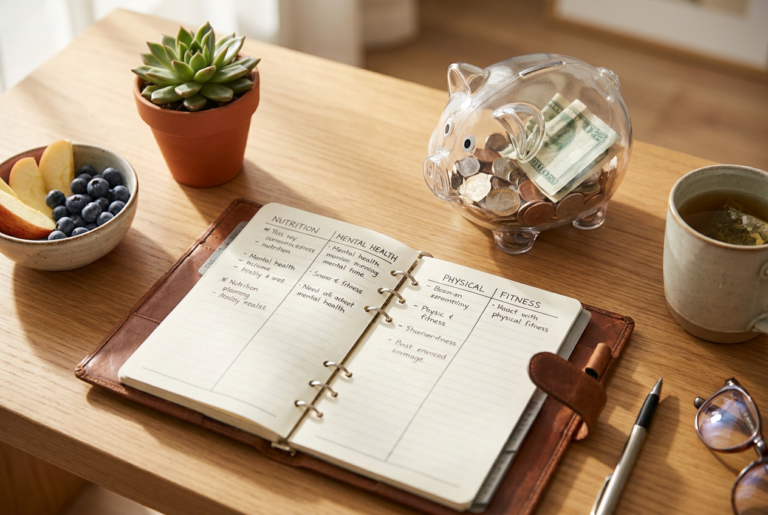
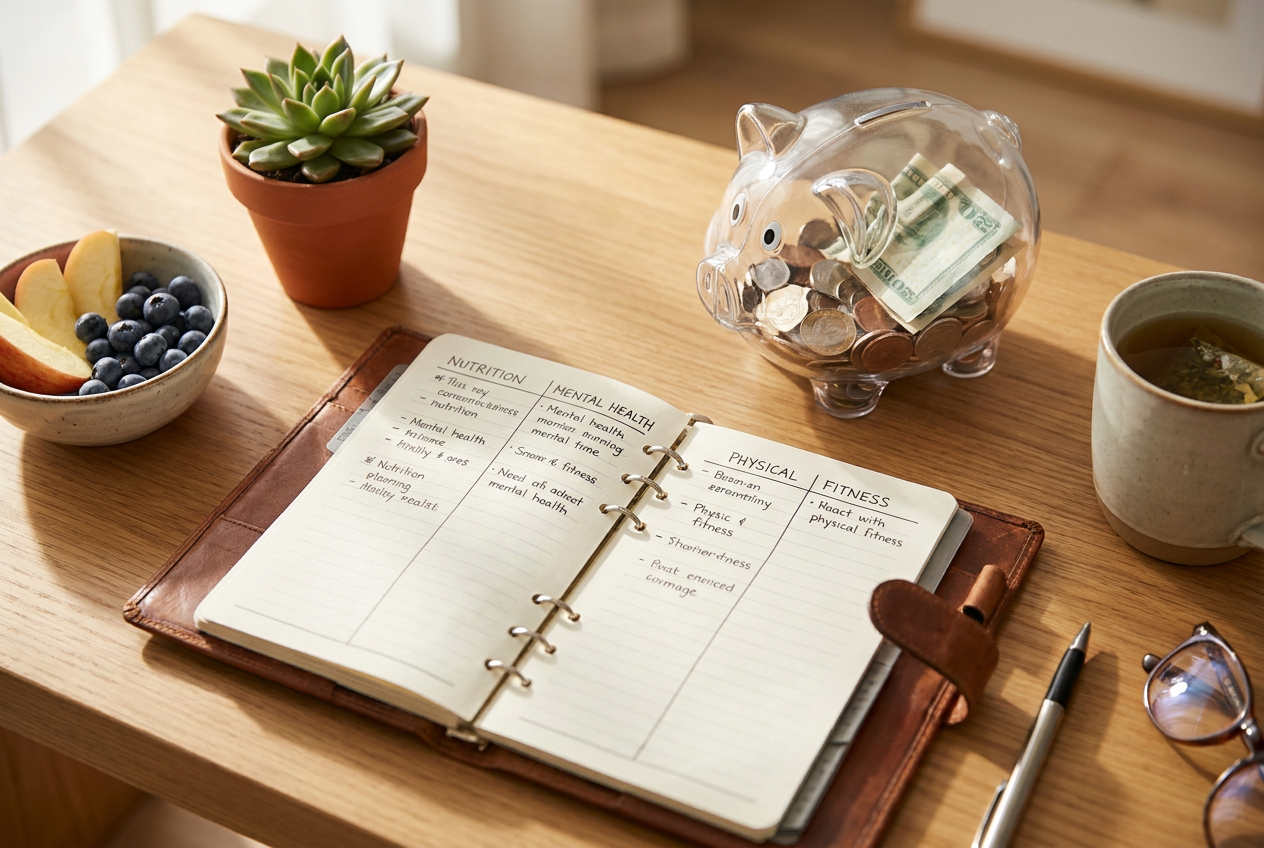
Divide your dedicated well-being funds into three distinct buckets: physical maintenance, mental recovery, and social connection. Assign specific dollar caps to each category based on your monthly cash flow.
For physical health, earmark money for baseline nutrition, movement, and preventative check-ups. For mental health, protect funds for therapy, journaling tools, or quiet spaces. Crucially, do not skip the social bucket. Allocate resources toward family outings, community groups, or animal well-being activities like local pet adoption walks that lower stress for you and your household.
If a bucket runs dry, pause non-essential spending in that specific category until the next cycle.
Step 4: Low-Cost, High-Impact Well-Being Investments
You do not need expensive subscriptions to improve your daily health. Swap a ninety-dollar gym tier for free community trail maps or bodyweight routines at home. Invest twenty dollars in a library card for stress-reducing reading material, or spend ten dollars on raw ingredients to cook nutrient-dense meals with family. For animal well-being, allocate a small monthly fund toward interactive puzzle toys instead of costly specialty gadgets. These minor adjustments stretch your dollars further, proving that meaningful physical and mental renewal relies on intentional habits rather than premium price tags.
Creating a Simple Monthly Well-Being Budget Template
Build your template by assigning fixed monthly dollar caps to three categories: physical, mental, and animal or family enrichment. For example, allocate fifty dollars for home workout gear, thirty dollars for mindfulness apps, and twenty dollars for pet health supplements. Keep this template separate from your primary household ledger to maintain clear boundaries. Review your totals every thirty days, shifting funds if you utilized a local library pass instead of a paid subscription. This straightforward tracking method prevents overspending while ensuring your daily habits consistently reflect your personal health priorities.
Adjusting Your Budget for Life Changes and Seasonal Shifts
Life rarely stays static, and your well-being budget must adapt right alongside it. When winter arrives, shift your physical wellness funds from outdoor running gear to a community indoor pool pass or a home resistance band set. If a demanding work project temporarily surges, dial back your social club dues and redirect those dollars into quick-prep healthy meal delivery services or stress-relief apps. Review your allocations quarterly. When family expenses or household veterinary bills fluctuate, scale your discretionary self-care items down by ten percent rather than cutting them entirely, ensuring your personal health remains a protected priority year-round.
Common Mistakes to Avoid When Budgeting for Well-Being
Treating health spending as an all-or-nothing proposition usually backfires. Avoid the trap of restricting your lifestyle so severely that you burn out within a month. Another frequent misstep is ignoring the financial needs of household pets, which leaves families scrambling when unexpected veterinary bills arise. Balance your strict savings targets with realistic fun money so you maintain your momentum. Building a sustainable routine takes time, flexibility, and honest adjustments rather than rigid perfection. Review your plan quarterly, adapt to changing life stages, and focus on steady, long-term habits that protect both your peace of mind and your bank account.
Frequently Asked Questions
What differentiates a traditional financial plan from a well-being budget?
Standard financial plans focus exclusively on debt, bills, and long-term retirement accounts while frequently overlooking the daily health expenses required to sustain earning power. A well-being budget specifically targets proactive physical, mental, and social investments to prevent burnout.
How do I determine which wellness expenses are genuinely necessary?
Review your past spending habits to separate authentic health needs from clever marketing campaigns pushed by the wellness industry. Focus strictly on activities and tools that demonstrably improve your daily mood, energy levels, and overall stability.
Is it possible to maintain this type of lifestyle plan on a tight income?
Affordable health investments deliver massive returns without requiring expensive gym memberships or premium supplement subscriptions. Utilizing public library resources, local outdoor trails, and home-based routines keeps costs minimal.
How frequently should I revise my wellness allocations?
Your spending caps ought to evolve alongside seasonal weather patterns and major life transitions. For instance, colder months might require shifting outdoor exercise funds toward indoor swimming passes or home resistance equipment.
What is the biggest pitfall to watch out for when tracking health expenses?
Many people fall into an all-or-nothing trap by implementing overly restrictive spending limits that ultimately cause rapid exhaustion. Additionally, failing to account for the physical and emotional enrichment needs of household pets frequently disrupts monthly targets.